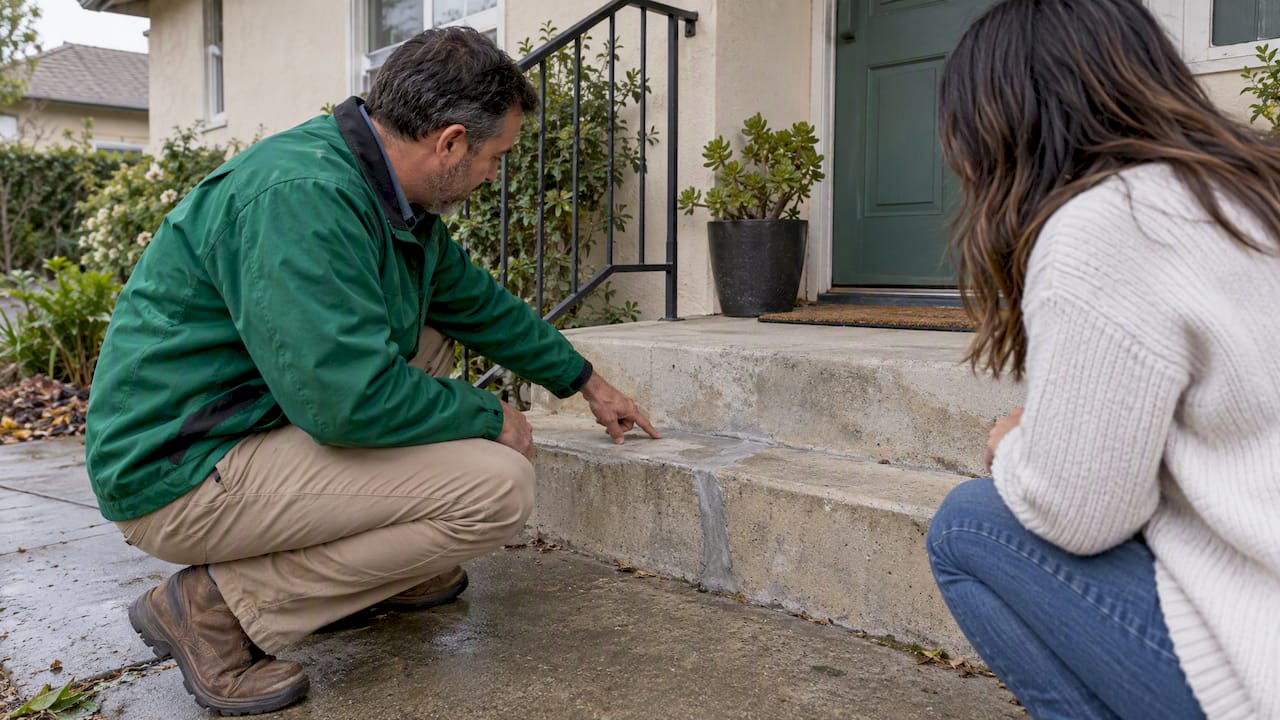
An escrow holdback is money set aside at closing to guarantee that specific, noncritical work will be finished after the sale is done. It lets a purchase move forward on schedule while a buyer, seller, and lender agree on exactly how and when the leftover work gets completed.
TL;DR:
- Escrow holdbacks are typically set at 120% to 150% of the estimated repair cost to cover potential overruns, and lender approval in writing is essential before closing.
- They are used mainly for noncritical, minor repairs such as landscaping or cosmetic work delayed by weather or permit delays, not for safety or structural issues.
- Clear, detailed contract language specifying amounts, completion criteria, inspection procedures, and timelines helps prevent disputes over fund releases.
- Holding funds from seller proceeds or a lender-controlled escrow ensures verified work completion through inspections, lien waivers, and signed certifications.
- Tax treatment generally counts holdback funds as part of the sale proceeds for sellers and not as deductible expenses for buyers, but individual cases vary and require professional review.
Table of Contents
- What an escrow holdback is (and how it differs from earnest money)
- Common situations where a holdback makes sense
- How an escrow holdback is arranged and released
- What lenders and loan programs require
- How to write holdback terms that hold up
- Risks buyers and sellers should watch for
- How disputes over holdback funds get resolved
- Tax implications of escrow holdback funds
- What a good buyer representative confirms before agreeing to a holdback
- How Ficustree helps buyers manage a holdback without missing a step
- Where to check the official rules
- Sources
- FAQ
What an escrow holdback is (and how it differs from earnest money)
An escrow holdback is a set amount of money, usually pulled from the seller’s proceeds or a lender-controlled account, that stays with a neutral third party until agreed-upon work is finished. Say a home inspection turns up a cracked exterior step two days before closing. Instead of delaying the sale, the parties can agree to hold $2,000 in escrow until the step is repaired and verified.
This is different from earnest money, which is a good-faith deposit a buyer puts down early in the process to show they are serious about the purchase. It is also different from an ordinary escrow account, which a mortgage servicer uses to collect property taxes and insurance over the life of the loan. A holdback is temporary, tied to one task, and released once that task is done.
Not every repair qualifies. Lenders generally sort issues into two buckets:
- Noncritical items: cosmetic repairs, landscaping, or minor punch list work that does not affect safety or habitability.
- Critical items: anything tied to structural integrity, safety, or the ability to get an occupancy permit, which usually must be fixed before closing.
Common situations where a holdback makes sense
Holdbacks tend to show up when the finish line for a sale and the finish line for a repair do not quite line up. A few patterns come up often:
- Weather-delayed work, like exterior paint or roofing that cannot be completed in winter.
- Unfinished landscaping, such as sod or fencing that a seller agreed to install.
- Permit sign-off delays, where the work is done but the city inspection has not been scheduled.
- Minor inspection findings, like a loose handrail or a leaky faucet that surfaced late in the process.
- New construction punch list items, where a builder has a short list of finishing touches left on move-in day.
Funding usually comes from one of two places: the seller’s sale proceeds, held back by the title or escrow company, or a lender-controlled completion escrow, funded from the loan itself. In a typical scenario, a seller who cannot finish a fence before closing agrees to let the buyer’s escrow process hold back the estimated repair cost until the fence is installed and verified.
How an escrow holdback is arranged and released
Setting up a holdback correctly takes more than a handshake. The terms need to live in two places: the purchase agreement, which states that a holdback will happen, and a separate escrow agreement, which spells out the amount, the conditions, and who signs off on release.
The escrow agent, sometimes the title company depending on your state, holds the funds and enforces the agreement’s terms without taking sides. If a loan is involved, the lender typically has to approve the arrangement in writing before closing, since the property’s marketability and the loan’s collateral value are both affected.
- Amount: usually the contractor’s estimate plus a contingency, often around 120% of the estimate to cover cost overruns, or the full fixed price if the work is under contract.
- Funding flow: money moves from seller proceeds or loan funds into a custodial escrow account at closing.
- Release triggers: a passed inspection, a signed completion certificate, lien waivers from contractors, and reviewed invoices confirming the work matches what was paid for.
Pro Tip: Get the release conditions in writing before closing, not after. A vague clause like “upon completion” invites disagreement over who decides the work is actually done.
What lenders and loan programs require
Lender rules vary, but the major loan programs share a common thread: holdbacks are for minor items only, and paperwork discipline is not optional. Under Fannie Mae’s guidelines, postponed improvements are allowed when they are minor, part of the sales contract, and completed within 180 days of the note date.
For FHA-insured loans, HUD’s escrow procedures require specific documentation, including Form HUD 92300, along with minimum escrow amounts of $500 or 1.5 times the cost of the deferred item, whichever is greater. HUD also requires lenders to keep a monitoring or tickler file so completion deadlines do not slip through the cracks.
Freddie Mac’s renovation programs follow a similar structure. Under CHOICERenovation, borrowers must oversee the renovation and supply documentation, and the lender holds funds in a Renovation Escrow Account pending an appraiser inspection before final disbursement.
- Postponed items under Fannie Mae guidelines must be completed within 180 days of the note date.
- HUD’s minimum escrow for FHA cases is $500 or 1.5 times the deferred item’s cost.
- Freddie Mac renovation escrows require appraiser sign-off before releasing final funds.
A common industry rule of thumb funds completion escrows at 120% to 150% of the estimated repair cost, though the exact figure is left to lender discretion under Fannie Mae’s postponed improvement rules. Get written lender approval and inspection documentation lined up before you count on a holdback to save your closing date.
How to write holdback terms that hold up
Clear contract language is what keeps a holdback from turning into a dispute six months later. Whether you are the buyer, the seller, or the agent drafting the paperwork, cover these points explicitly:
- State the exact amount and how it was calculated, whether that is the contractor’s estimate plus a contingency or a fixed completion contract price.
- Define completion criteria in plain language, including who inspects the work and what documents prove it is done, such as a certificate of completion, a Form 1004D or lender equivalent, lien waivers, and paid invoices.
- Set a firm timeline, plus rules for extending it if weather or permitting causes delays.
- Spell out dispute resolution and what happens to leftover funds once the work is finished.
- Name the escrow agent’s duties and fees, and state clearly who pays for inspections or ongoing monitoring.
Pro Tip: Treat the escrow agreement like its own contract, not an afterthought clause. Reading up on mortgage contingency language before you draft holdback terms helps you spot gaps a lender might flag later.
Risks buyers and sellers should watch for
A holdback solves a timing problem, but it creates a few of its own. The most common failure point is underfunding: if the escrow amount was based on a rough guess rather than a real bid, the money runs out before the work is finished. Missed inspections, unresolved lien claims from unpaid contractors, and lenders invoking the holdback to cover a shortfall are the next most frequent issues.
One reality catches first-time buyers off guard: escrow agents enforce the paperwork, but they rarely chase down a slow contractor. The buyer or seller who agreed to the repair is usually the one responsible for tracking deadlines and submitting proof of completion.
- Confirm lender acceptance of the holdback in writing before closing.
- Get a documented, itemized estimate, not a verbal quote.
- Schedule the completion inspection as soon as the work wraps up.
- Collect lien waivers from every contractor paid out of the escrow.
- Keep copies of every invoice, inspection report, and signed release.
How disputes over holdback funds get resolved
Most holdback disputes come down to one disagreement: whether the work was actually completed to the standard the contract described. When that happens, the escrow agreement’s own terms usually govern the process, since escrow agents are not authorized to release funds based on one party’s word alone.
The first step is typically a joint inspection, where both parties, or their representatives, review the completed work against the original scope. If they do not agree, most escrow agreements point to a specific resolution path, often mediation or arbitration, rather than releasing funds to either side unilaterally.

In loan-related holdbacks, the lender’s completion inspection carries extra weight, since the Fannie Mae framework ties fund release to a satisfactory inspection report, such as a Form 1004D, rather than to buyer or seller opinion. This is one reason a vague completion clause causes so much friction. When “finished” is not defined with a specific inspection standard and required documents, both sides end up arguing over a judgment call the contract should have settled in advance. Escrow agreements that name a specific inspector, a specific form, and a specific timeline rarely end up in a standoff.
Tax implications of escrow holdback funds
Escrow holdback funds are not treated as income to either party simply because they sit in a third-party account. For the seller, the money is generally still counted as part of the total sale proceeds, since it represents funds they would have otherwise received at closing if the work had already been done. Once the holdback is released, whether to the seller after completion or spent on the repair itself, it typically factors into the seller’s cost basis and gain calculation for the sale, the same as any other closing adjustment would.
For the buyer, funds used to pay for repairs out of a holdback are not usually deductible as a moving or purchase expense, though capital improvements can affect the home’s cost basis down the line. Because tax treatment depends on how the holdback is structured, whether it is seller-funded, lender-funded, or structured as a credit, and on the buyer’s or seller’s overall tax situation, this is an area where a qualified tax professional or CPA should review the specific transaction rather than relying on general rules of thumb.

What a good buyer representative confirms before agreeing to a holdback
A buyer representative worth having will not treat a holdback as a convenient way to save a closing date. Before suggesting one, they confirm three things: that the lender has approved it in writing, that the completion criteria and required documents are spelled out clearly, and that the repair estimate comes from a credible contractor, not a guess. A step-by-step checklist helps first-time buyers keep track of deadlines and paperwork instead of losing them in the shuffle of a closing week. When an issue touches safety, structural integrity, or occupancy approval, the right call is to insist the work gets done before closing, not to paper over it with an escrow account.
— Anand
How Ficustree helps buyers manage a holdback without missing a step
Coordinating a holdback means chasing lender sign-off, scheduling inspections, and tracking documents, all while everything else about closing is happening at once. Ficustree pairs first-time buyers with direct representation that covers exactly this kind of detail work.

- Contract review to make sure holdback language names an amount, a timeline, and a clear completion standard.
- Lender coordination so approval is documented before it becomes a closing-day surprise.
- Inspection scheduling to keep completion deadlines from slipping.
- Documentation tracking for invoices, lien waivers, and sign-off forms.
Visit the buyer page to see how the Direct Path works for your purchase.
Where to check the official rules
For exact figures and forms, go straight to the source. Fannie Mae’s postponed improvement guidance covers completion escrows and timelines, HUD’s 4145.1 REV-2 handbook details FHA escrow procedures and forms, and Freddie Mac’s renovation borrower tips explain completion-escrow expectations for renovation loans. For contract-side contingency language, this loan contingency guide is a useful reference.
Sources
- Requirements for Verifying Completion and Postponed Improvements | Fannie Mae
- 4145.1 REV-2 — HUD escrow procedures (Chapter 5)
- Mortgage borrower tips (CHOICERenovation) | Freddie Mac
FAQ
What is the purpose of an escrow holdback?
An escrow holdback lets a home sale close on schedule while money is set aside to guarantee that specific, unfinished, noncritical work gets completed afterward. It protects the buyer from losing leverage once the sale is final and protects the seller from a delayed closing over minor issues.
Who pays for an escrow holdback?
The funds usually come from the seller’s sale proceeds when the seller is responsible for the unfinished work, or from the loan itself when a lender sets up a completion escrow. Either way, the amount is typically based on a contractor’s estimate plus a contingency, commonly around 120% of that estimate under Fannie Mae’s guidelines.
Do lenders allow escrow holdbacks?
Yes, but only for minor, noncritical items, and only with written approval. Programs like Fannie Mae and FHA/HUD permit postponed improvements under specific conditions, including completion deadlines and required inspection documents, while anything tied to safety or structural integrity generally must be fixed before closing.
How do you set up an escrow holdback?
The terms go into both the purchase agreement and a separate escrow agreement that names the exact amount, the completion criteria, required inspections, and the release process. Getting lender approval in writing and a documented contractor estimate before closing keeps the arrangement from becoming a dispute later.
Recommended
- How to Make a Competitive Home Offer in 2026
- California Closing Costs Breakdown for First-Time Buyers
- Escrow Process for First-Time Buyers: California Guide
- 3 Percent Down Mortgage for First-Time Buyers

Leave a Reply